Hurricane Damage Lawyer for Wind and Storm Insurance Claims
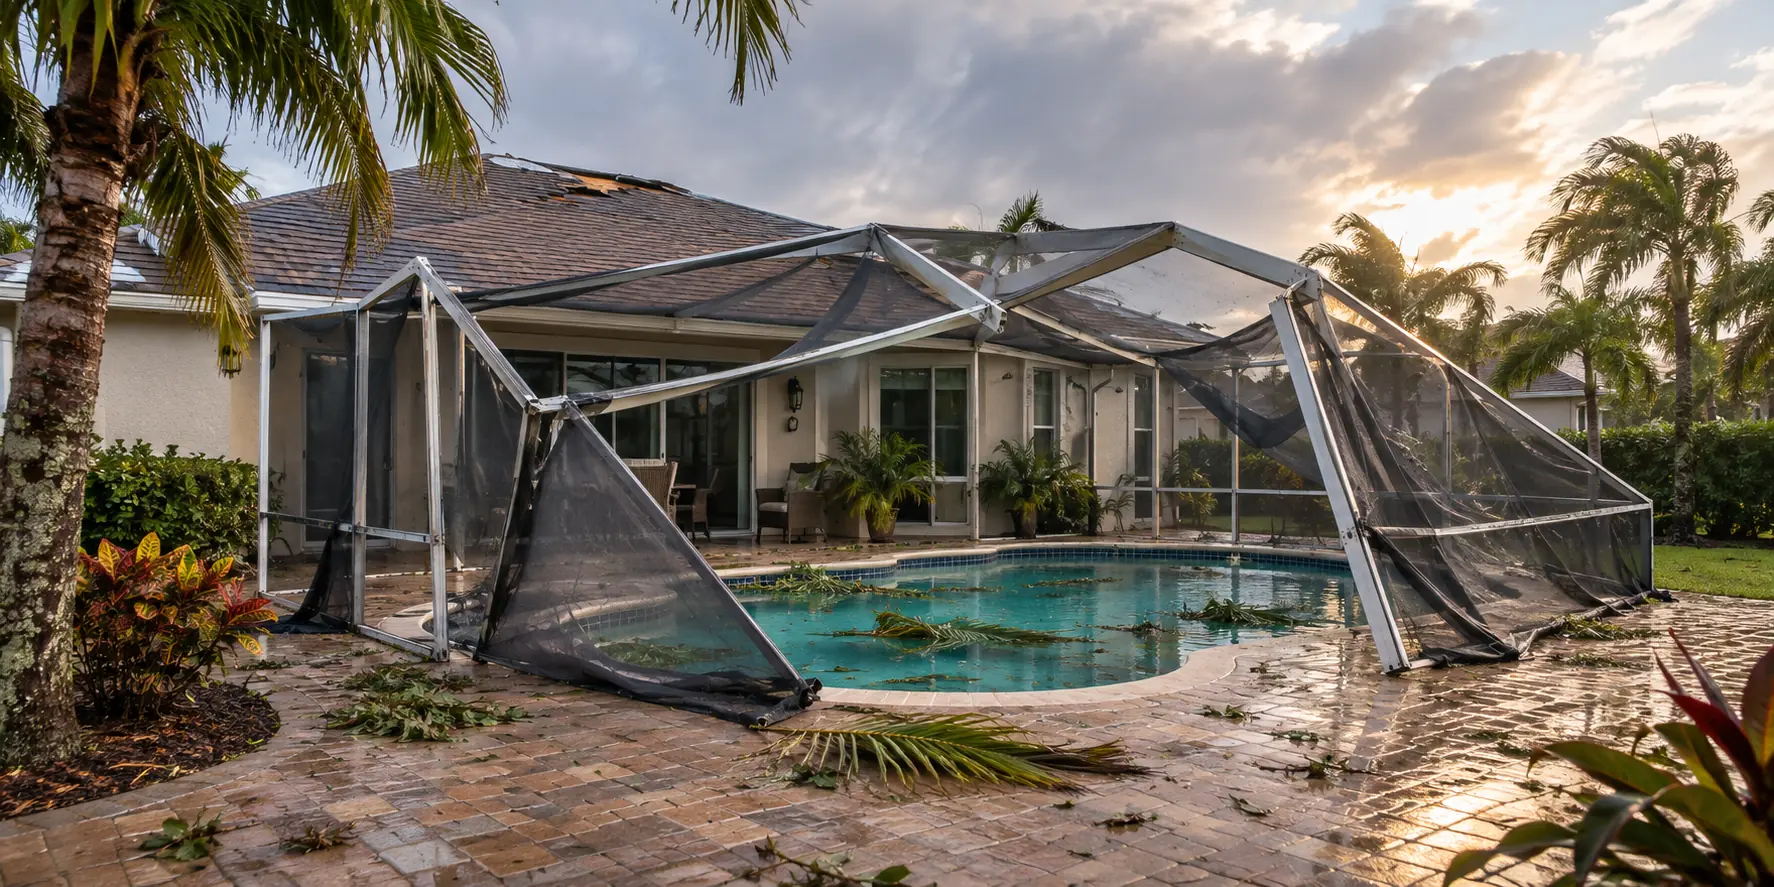
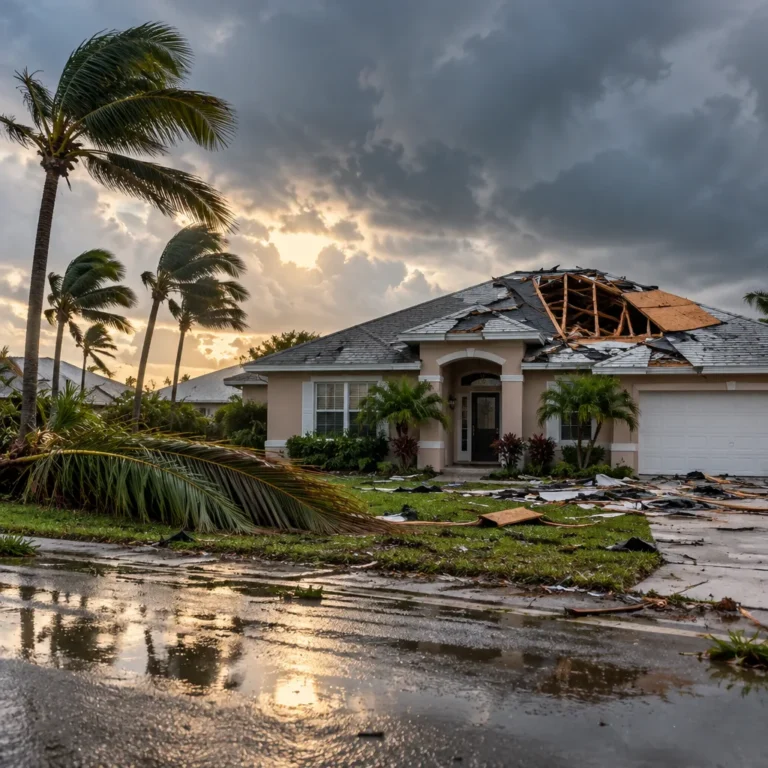
After a hurricane or windstorm, insurers often dispute what the wind caused and how much repairs cost. Gomez Law helps Florida homeowners, condo owners and associations with denied or underpaid hurricane and wind claims. Call (305) 720-2601.
Hurricane Deductibles and Wind vs. Water
Most Florida property policies carry a separate hurricane deductible, often a percentage of the dwelling coverage rather than a fixed dollar amount. Check the declarations page of your policy to see yours.
Insurers also separate wind damage from flood. Wind, and rain that enters through openings the wind created, is usually covered by your property policy. Rising water from storm surge or flooding usually needs a separate flood policy. Many disputes turn on which one caused the damage.
Common Hurricane Claim Disputes
Deadlines After a Storm
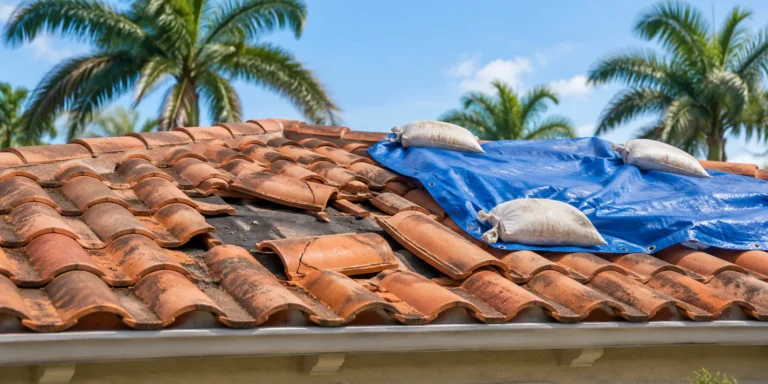
Florida gives you 1 year from the date of loss to report a new or reopened claim, and 18 months for a supplemental claim when you find more damage (Fla. Stat. 627.70132). Take photos before repairs, keep receipts for emergency work, and save every letter from the insurer.
Condo Buildings After a Hurricane
In a condo, the association’s policy covers the building as originally built and the common elements, and each owner’s policy covers interior items (Fla. Stat. 718.111(11)). We help associations with claims against their insurer, and owners with claims under their unit policy.
How We Help With Hurricane and Wind Claims
Your Attorney: Eduardo Gomez, Esq.
Eduardo Gomez handles the firm’s property insurance cases. He has practiced first-party insurance litigation in Florida state and federal courts since founding the firm in 2008, and before that he worked in insurance coverage and defense, so he knows how insurers evaluate claims. At his former firm he was primarily responsible for its Hurricane Wilma cases, more than 1,000 claims.
Frequently Asked Questions
Related Pages
Talk With a Hurricane Damage Lawyer
Call (305) 720-2601 or schedule a consultation at our Coral Gables office, 145 Almeria Avenue. Office hours: Monday to Friday, 9 AM to 5 PM.